Job Costing for Manufacturers: The Complete Guide

Our guide to cost of goods sold covers the accounting formula that produces COGS at the company level. Job costing is the operational system that actually produces an accurate cost figure for one specific job, the input every margin calculation on this site ultimately depends on. Get job costing wrong, and every downstream number, gross margin, a quote’s target price, a customer’s true profitability, inherits that error without anyone necessarily noticing where it came from.
What Is Job Costing?
Job costing is a method of tracking the cost of production separately for each individual job, order, or batch, rather than averaging cost across everything produced during a period. It’s the standard costing method for businesses that make custom, unique, or made-to-order products, contract manufacturers, custom fabricators, construction, and any shop where job number 4521 is genuinely different from job number 4522, and needs its own cost record to be priced and evaluated accurately.
This is distinct from process costing, used by businesses that produce large volumes of identical or near-identical units continuously, chemical plants, food processing, paper mills, where tracking cost per individual unit would be impractical and unnecessary, and total production cost gets averaged across everything produced in a period instead.
| Job Costing | Process Costing | |
|---|---|---|
| Used when | Products are unique, custom, or made in distinct batches | Products are identical and produced continuously |
| Cost tracked | Per individual job or order | Averaged across a production process or department |
| Typical industries | Contract manufacturing, custom fabrication, construction, furniture | Chemicals, food and beverage, paper, basic materials |
| Pricing implication | Each job can and should be priced individually | Pricing is typically set per unit off an averaged cost |
The Three Components of Job Cost
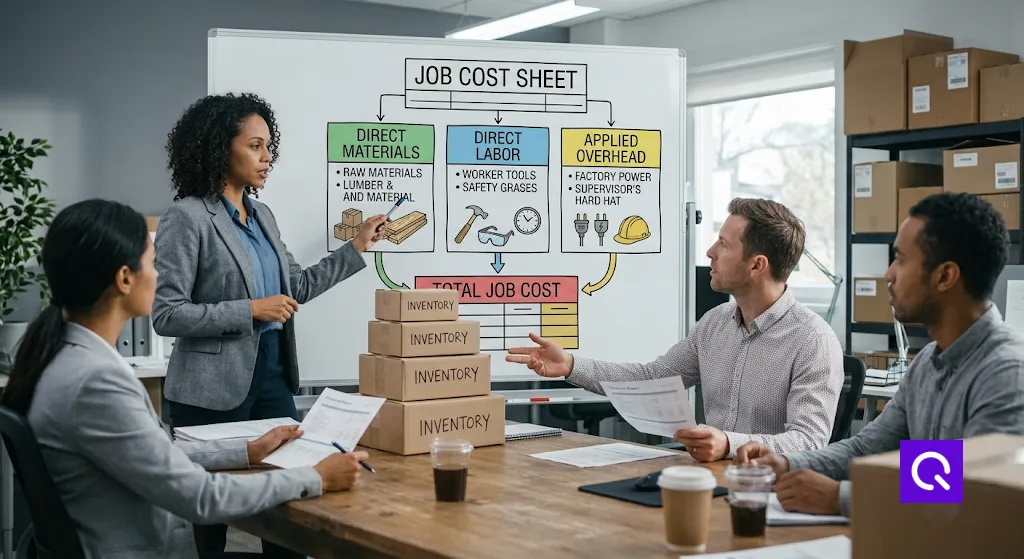
Direct materials. The raw materials and components that go directly into the specific job, tracked at actual cost, not an estimate, once the job is complete. This is usually the most straightforward component to track accurately, since materials are typically purchased or issued against a specific job number.
Direct labor. The hours worked directly on the job, multiplied by the labor rate, tracked through time cards, labor tickets, or a shop floor data collection system tied to the specific job number. This component breaks down most often when workers split time across multiple jobs in a shift without clocking in and out of each one separately, which quietly spreads one job’s labor cost onto another’s.
Applied manufacturing overhead. The portion of factory overhead, utilities, equipment depreciation, supervisor salaries, facility costs, allocated to the specific job, since these costs can’t be traced directly to one job the way materials and labor can. This gets applied using a predetermined overhead rate, calculated in advance and applied throughout the period based on some measurable activity the job consumes.
How Overhead Actually Gets Applied to a Job
The predetermined overhead rate is calculated once, typically at the start of a fiscal year, using estimated figures:
Predetermined Overhead Rate = Estimated Total Overhead / Estimated Total Allocation Base
The allocation base is whatever activity most closely drives overhead cost in a specific shop, commonly machine hours, direct labor hours, or direct labor dollars. A shop with $600,000 in estimated annual overhead and 20,000 estimated annual machine hours would set a rate of $600,000 / 20,000 = $30 per machine hour. Every job that runs through the shop gets overhead applied at $30 for every machine hour it consumes, regardless of what the shop’s actual overhead turns out to be by year-end, which is why this figure is called an estimate applied throughout the period, reconciled against actual overhead only after the fact.
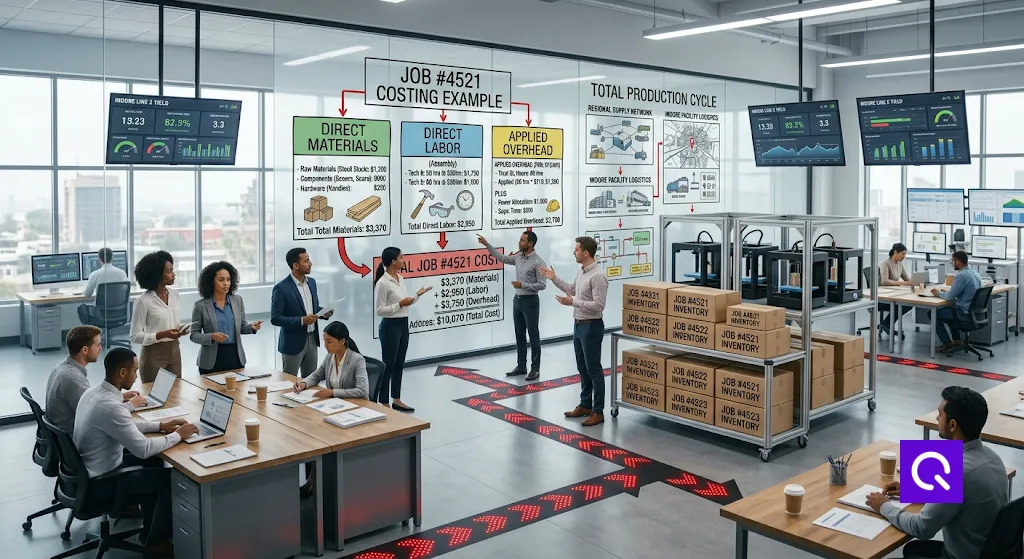
Job #4521: materials, labor, and applied overhead combine to a $10,070 total cost.
A complete worked example: Job #4521 uses $8,200 in direct materials, 40 hours of direct labor at $28 per hour ($1,120), and runs on the machine for 25 hours. Applied overhead is 25 hours × $30 = $750. Total job cost: $8,200 + $1,120 + $750 = $10,070. If the job bills at $14,000, gross margin on the job is ($14,000 − $10,070) / $14,000 = 28.1%, the exact figure that belongs in the kind of job-level tracking covered in our guide to tracking gross margin by customer.
Common Job Costing Mistakes
Using a stale overhead rate. A predetermined overhead rate calculated two or three years ago, before equipment was added, a facility expanded, or utility costs rose, systematically misstates the true overhead cost of every job run since then. Overhead rates should be revisited at least annually, and sooner if the shop’s cost structure changes meaningfully.
Choosing the wrong allocation base. A shop that has automated significantly, shifting cost from direct labor toward machine time and equipment depreciation, but still allocates overhead based on labor hours, will systematically overcost labor-heavy jobs and undercost machine-heavy ones, distorting which jobs actually look profitable.
Tracking estimates instead of actuals. Job costing only produces a reliable number when materials and labor are tracked at their real, actual cost once the job is complete, not carried forward at the original quoted estimate. A shop that never reconciles estimated cost against actual cost has no way to know whether its quoting process is accurate or whether specific job types consistently run over.
No feedback loop back into pricing. Job costing that exists only to close the books, without ever being compared back against the original quote, misses its most useful purpose. The gap between quoted cost and actual cost, tracked over time, is exactly what reveals whether a shop’s quoting formulas need adjustment, which connects directly to the pricing mistakes covered in our guide to gross margin vs. markup.
Job Costing Systems: Why Spreadsheets Eventually Break Down
A spreadsheet-based job costing system works reasonably well at low job volume with a small team maintaining it consistently. It becomes fragile as job volume grows, since it depends entirely on someone manually pulling labor tickets, material issues, and machine hours into the right job record every time, with no automatic check for a job that was never closed out or a labor hour that never got coded. Most ERPs, Prophet 21, NetSuite, SAP, and Epicor among them, offer built-in job costing modules that solve the manual data entry problem, but as covered in our related research on why an ERP alone won’t save your margins, most of them still report the resulting job cost after the job has closed, at month-end, rather than surfacing it while a job is still in progress and cost drift can still be corrected.
Why Everything Downstream Depends on Getting This Right
Job costing is the operational engine behind nearly everything else covered on this site. It produces the actual direct materials and labor figures used in the COGS formula. It’s the basis for calculating gross margin at the job level rather than only as a blended company-wide average. Running a job’s actual numbers through our gross margin calculator only produces a trustworthy result if the job cost feeding it was tracked accurately in the first place. The distinction between fixed and variable overhead, central to our contribution margin vs. gross margin guide, depends entirely on how a shop’s job costing system classifies its overhead allocation. Comparing a shop’s margin against the right peer group, as covered in our guide to good gross margin for a contract manufacturer, requires knowing that job costing methodology is at least roughly comparable between the two. Rolling job cost up to see true profitability by account, covered in our guide to tracking gross margin by customer, is only as accurate as the underlying job records. And in a due diligence process, covered in our guide to gross margin vs. EBITDA in M&A, inconsistent job costing practices across a target’s history are exactly the kind of issue a buyer’s quality of earnings review is built to surface.
Frequently Asked Questions
What is job costing in accounting?
Job costing is a method of tracking production cost separately for each individual job or order, rather than averaging cost across everything produced in a period. It’s used by businesses that make custom, unique, or made-to-order products.
What is the difference between job costing and process costing?
Job costing tracks cost per individual job, used when products are unique or custom. Process costing averages cost across a continuous production process, used when products are identical and produced in high volume, such as chemicals or food processing.
How do you calculate applied overhead?
Applied overhead equals the predetermined overhead rate multiplied by the amount of the allocation base (such as machine hours or labor hours) a specific job consumes. The predetermined rate itself is calculated by dividing estimated total overhead by an estimated total allocation base for the period.
What is a job cost sheet?
A job cost sheet is a record that accumulates the direct materials, direct labor, and applied overhead for one specific job, producing a total job cost that can then be compared against the price quoted or billed for that job.
Which businesses use job costing?
Job costing is standard in contract manufacturing, custom fabrication and machining, construction, custom furniture and cabinetry, printing, and any business where each order or project is different enough to require its own cost tracking rather than an averaged per-unit cost.
Is job costing the same as contract costing?
The two are closely related and the terms are sometimes used interchangeably. Contract costing is typically used to describe job costing applied to large, long-duration projects, such as construction contracts, where cost gets tracked over an extended timeline rather than a single short production run.
The Bottom Line
Job costing is the operational discipline that turns the abstract idea of cost of goods sold into an actual, job-by-job number a business can price against, evaluate customers with, and trust when it flows into a margin calculation. A shop with excellent formulas for gross margin and pricing, built on top of inconsistent or outdated job costing, is still making decisions on inaccurate data. Fixing the input matters more than refining the formula downstream of it.
If you’re not confident your own job costing is producing numbers accurate enough to trust, Quanzar’s free 10-minute margin audit checks your last several jobs and shows exactly where the gaps are.