Contribution Margin vs Gross Margin: Key Differences

Contribution Margin vs Gross Margin: Gross margin and contribution margin can sit five, ten, even twenty points apart on the exact same job, and both numbers can be correct at the same time. The gap between them is not a rounding error or a reporting inconsistency. It comes from a genuinely different question each metric is built to answer, and mixing them up leads to two very different kinds of mistakes: pricing decisions made on the wrong number, and short-term job decisions made using a metric that was never built for that purpose.
This guide assumes familiarity with the basic gross margin formula, covered in full in our complete guide to gross margin. The focus here is when and why contribution margin gives a different, and sometimes more useful, answer, and where relying on gross margin alone can lead a manufacturer to turn down profitable work or keep pricing a product line long past the point it makes sense.
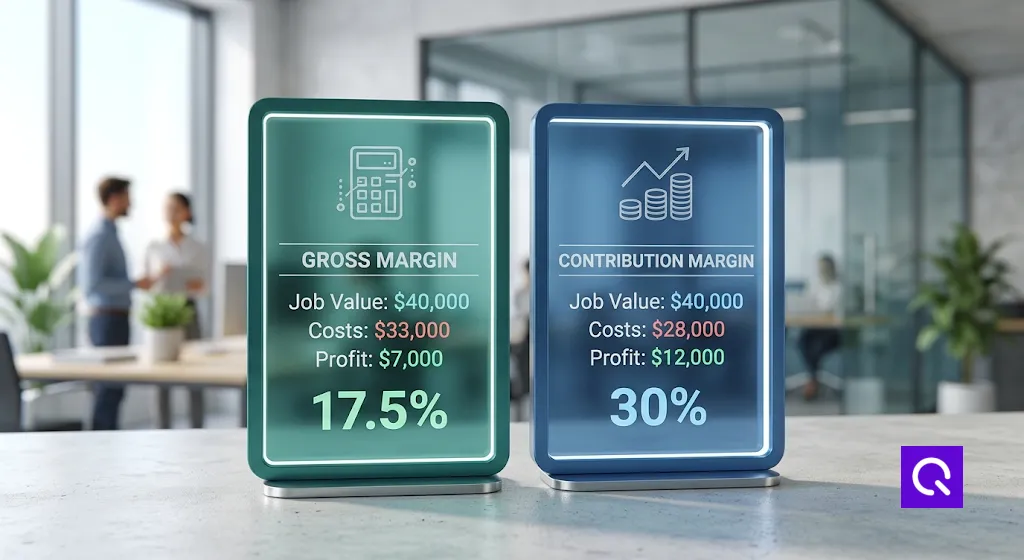
The same $40,000 job: 17.5% gross margin, 30% contribution margin.
The Real Distinction: What Counts as a Cost, Not Just How Much
Gross margin subtracts cost of goods sold from revenue, and COGS is defined by accounting convention, direct materials, direct labor, and manufacturing overhead that gets allocated to production, including overhead that does not actually change with volume. A portion of the factory lease, for example, often gets allocated across units produced as part of standard job costing, even though the lease payment itself is fixed and would be identical whether the factory ran at 50% capacity or 100%.
Contribution margin ignores that accounting classification entirely and asks a different question: which costs actually change if one more unit gets produced or one more job gets accepted? Contribution margin subtracts only true variable costs, costs that rise and fall directly with volume, regardless of whether accounting rules would classify them as COGS or as an operating expense. Fixed costs, the factory lease, salaried supervisors, equipment depreciation, insurance, get left out of the calculation entirely, not allocated differently, but excluded.
Contribution Margin = Revenue − Variable Costs
Contribution Margin Ratio (%) = (Contribution Margin / Revenue) × 100
In a lot of manufacturing businesses, gross margin and contribution margin land close to each other, because most of what sits in COGS is genuinely variable. The two numbers diverge meaningfully in exactly the situations covered below, and that divergence is where contribution margin earns its place as a separate metric rather than a redundant one.
A Job Decision Where the Two Metrics Disagree
Consider a contract manufacturer with a standing 30% gross margin target for accepting new work. A customer offers a rush job at $40,000. Direct materials come to $22,000 and additional variable labor comes to $6,000, both costs that exist only because this specific job gets run. Standard job costing also allocates $5,000 of factory overhead to the job, the shop’s usual method of spreading fixed costs like rent and equipment depreciation across whatever work is currently running.
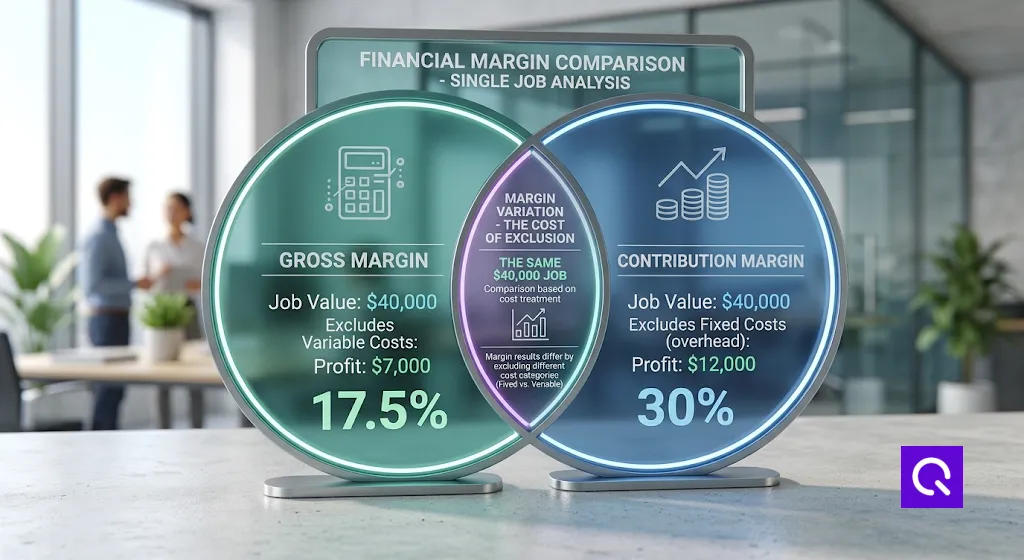
Under standard costing, COGS totals $33,000 and gross profit is $7,000, a gross margin of 17.5%, well under the 30% target. On that basis alone, the job looks like an easy pass.
Looked at through contribution margin instead, the $5,000 in allocated overhead is fixed. It gets spent whether this job runs or not, the lease payment and the equipment depreciation do not change based on whether this specific rush order is accepted. Contribution margin on the job is $40,000 − $22,000 − $6,000 = $12,000, a 30% contribution margin. If the shop has idle capacity, a machine and crew that would otherwise sit unused, that $12,000 is money the business would not otherwise collect, going toward fixed costs and profit that exist either way.
Rejecting the job because it fails a 30% gross margin test, in a shop that has open capacity and nothing better to fill it with, leaves $12,000 on the table for no real benefit. The fixed overhead gets paid out of the business’s other work regardless of this one decision.
The Caution That Comes With This Logic
This is also exactly the reasoning that, applied carelessly, turns into chronic underpricing. The contribution margin argument for accepting a lower-margin job only holds when three conditions are genuinely true: real idle capacity exists, accepting the job does not displace higher-margin work that would otherwise fill that same capacity, and accepting it does not set a customer’s ongoing price expectation below what the relationship should actually be priced at long term. A one-time rush job from a new customer with slack capacity is a reasonable candidate for this logic. A recurring customer relationship priced this way indefinitely is a margin problem wearing a contribution margin justification.
Break-Even Analysis: What Contribution Margin Is Actually Built For
Contribution margin is the number behind break-even analysis, and gross margin cannot do this calculation on its own, because break-even is fundamentally a question about fixed costs, which gross margin was never built to isolate cleanly.
Break-Even Point (units) = Fixed Costs / Contribution Margin per Unit
A shop with $150,000 in monthly fixed costs, rent, salaried staff, insurance, and equipment depreciation, and an average contribution margin of $500 per unit on its main product line, needs to sell 300 units a month just to cover fixed costs before any profit exists. Every unit beyond 300 contributes $500 directly to profit, since fixed costs are already covered. This is the calculation behind deciding whether a new piece of equipment, a new hire, or a new facility lease is actually supportable at current volume, and it only works with contribution margin as the input.
When to Use Gross Margin vs. Contribution Margin
| Situation | Use This Metric |
|---|---|
| External reporting, board decks, comparing to industry benchmarks | Gross Margin |
| Setting a standard quoting or pricing policy | Gross Margin |
| Deciding whether to accept one specific job with idle capacity | Contribution Margin |
| Break-even analysis, or deciding if new equipment or headcount is supportable | Contribution Margin |
| Deciding whether to discontinue a product line | Contribution Margin, with care (see caution below) |
| Comparing profitability across companies or industries | Gross Margin |
The product line discontinuation case deserves its own caution, similar to the idle capacity case above. A product line can show a low or negative gross margin while still carrying a positive contribution margin, meaning it covers its own variable costs and contributes something toward the fixed costs the rest of the business already carries. Discontinuing it does not eliminate those fixed costs, rent and salaried staff do not disappear because one product line goes away, it just means the remaining product lines now have to cover them alone. Cutting a positive-contribution product line without a plan to either replace its contribution or genuinely reduce the fixed costs it was helping to cover often makes overall profitability worse, not better, even though the discontinued line looked like the problem on a gross margin basis.
This is the exact blind spot that shows up in Quanzar’s research into where contract manufacturers lose margin, where product and customer decisions made on a single margin figure, without checking what’s actually fixed versus variable underneath it, turn out to have the opposite effect from what was intended.
Frequently Asked Questions
Is contribution margin the same as gross margin?
No. Gross margin subtracts cost of goods sold, which includes some fixed costs allocated to production, from revenue. Contribution margin subtracts only true variable costs, excluding all fixed costs regardless of how they’re classified for accounting purposes. The two can be close or far apart depending on how much of COGS is genuinely fixed.
What is a good contribution margin?
There’s no universal target, since it depends heavily on the cost structure of the specific business. Contribution margin is generally higher than gross margin for the same company, since it excludes all fixed costs rather than just costs classified outside of COGS. It’s more useful compared against a company’s own fixed cost base and break-even point than against an industry benchmark.
How do you calculate the contribution margin ratio?
Contribution Margin Ratio = Contribution Margin / Revenue, expressed as a percentage. It answers what portion of each revenue dollar is left after variable costs, before any fixed costs are covered.
Can contribution margin be negative?
Yes, and it’s a more serious signal than a negative gross margin. A negative contribution margin means variable costs alone exceed revenue, so the business loses money on every additional unit sold before fixed costs are even considered. Producing more in that scenario makes the loss larger, not smaller.
Does gross margin include fixed costs?
Partially. Fixed production costs that get allocated to COGS as part of standard job costing, such as a portion of factory rent or equipment depreciation, are included in gross margin. General fixed costs outside of production, like office rent or salaried administrative staff, are not. Contribution margin excludes fixed costs of every kind, which is the core reason the two metrics diverge.
Should a manufacturer ever accept a job that doesn’t meet its gross margin target?
Sometimes, if the job has a positive contribution margin and there’s genuine idle capacity that would otherwise go unused. This should be treated as a deliberate, occasional exception with clear criteria, not a standing practice, since relying on it routinely is how a business quietly trains its customers and its own sales team to expect below-target pricing.
The Bottom Line
Gross margin and contribution margin are not competing ways of measuring the same thing. They answer different questions, one built for external reporting and pricing strategy, the other built for short-term, incremental decisions about a specific job, product, or piece of capacity. Using the wrong one for the decision at hand is how a business ends up rejecting profitable work in the name of protecting a margin target, or keeping a genuinely unprofitable product line alive because contribution margin logic got stretched further than it was meant to hold.
If it’s unclear which jobs, customers, or product lines in your own business are actually running which way, Quanzar’s free 10-minute margin audit breaks down your last several jobs at the level of detail this kind of decision actually requires.